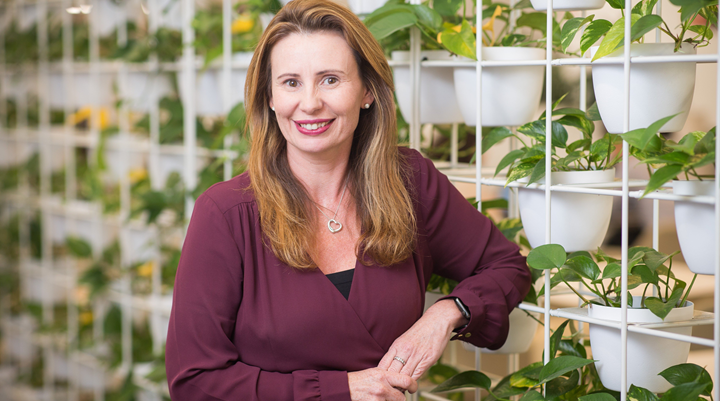
Nicole Battistessa spent more than two decades inside some of the world’s biggest FMCG companies before wine entered her job description earlier this year. Seven months after becoming managing director of Vinarchy Australia and New Zealand, following senior roles at Nestlé, Unilever and Kimberly-Clark, she sounds the slightest bit surprised by how natural the move feels. “I feel like I have found my home,” she told Inside FMCG. Vinarchy is barely a year old; some of the brands inside it d
ate to the 19th century. And Battistessa has arrived at a moment when one of the world’s oldest consumer categories is having to reconsider how, when and why people buy it.
Formed in 2025 from Accolade Wines and Pernod Ricard Winemakers, Vinarchy carries a portfolio of more than 40 brands globally, led by Australia’s own Jacob’s Creek, Hardys and Spain’s Campo Viejo. The inheritance is enviable but the market conditions are less so. Global wine consumption declined in 2025, with Australia down three per cent. At the bottle shop, though, the decline was milder, with off-trade wine volumes dropping just one per cent in the year to June 2026. Vinarchy has scale, heritage and distribution; Battistessa’s job is to make those assets useful to a wide range of shoppers.
Her outsider status may help. Battistessa has spent more than 25 years in global FMCG across the APAC region, and she speaks about wine with the alertness of somebody who has entered a venerable club and immediately started moving the furniture. “Coming in here, we are really just making that transition now,” she said. Historically, she argues, what grapes had been grown could determine the innovation agenda. Her previous categories had begun with another premise, which was to find the consumer need, then build around it – a supermarket-minded proposition. Wine has always paid close attention to what goes into the bottle. Battistessa wants the same attention paid to the person buying it.
Gen Z and the 750ml bottle
It becomes particularly pertinent with younger drinkers, who have acquired an unclear status in alcohol commentary. Battistessa is sceptical of the idea that they have abandoned drinking. “I would say that the younger generation aren’t rejecting wine,” she said. Current IWSR evidence lends her some support and reported the drinking rate among legal-age Gen Z consumers across 15 global markets reached 74 per cent in 2026, close to 76 per cent for the adult population overall. The harder problem for wine is competition. Younger adults can choose among RTDs, cocktails, beer, spirits and alcohol-free drinks, usually sold in formats designed around portability, portion and occasion. “There are green shoots coming through everywhere,” Battistessa said. “What’s probably happened, though, is the wine industry hasn’t leaned in enough to that generation and understood what they’re looking for. They want stuff that’s easy to understand. They want to have options that are convenient that fit in with their social occasions and celebrations, etc. That hasn’t necessarily been the focus of wine in a 750ml bottle historically.”
Wine’s most persistent piece is just that – the 750ml bottle. It arrives with an implied script to open it, pour several glasses, preferably over dinner, and find somebody to share it with. Battistessa sees room to ease that convention. “We are looking at every possible opportunity that fits in with a consumer’s need based on where they are on that occasion. So everything’s on the table right now.” Wine Australia has found younger consumers are more inclined to buy alternative packaging, while 187ml bottles have recorded growth in Australia from a small base. Its research also identifies cans, PET, paper bottles and lighter glass as avenues for convenience and lower emissions.
Moderation is now about choice
The bottle question leads naturally to alcohol strength, although Battistessa adamantly separates ‘moderation’ from ‘low’. Drinking less, she points out, can be as simple as having one glass instead of two. The wider numbers support her, as Australia’s per capita alcohol consumption fell to 9.8 litres in 2023-24, its lowest level in almost a decade, while American market research firm NIQ found 38 per cent of Australian drinkers now describe themselves as occasional but mindful.
Still, taste remains the gatekeeper. “We won’t compromise the product to deliver against trend,” Battistessa noted, adding that Vinarchy’s global innovation team is spending considerable time on lower-alcohol products that preserve the quality consumers expect. It’s also becoming abundantly clear that moderation is not about abstinence, but diversity. Endeavour Group recently found that 48.5 per cent of non-alcoholic beer purchases at BWS and Dan Murphy’s were bought alongside an alcoholic item. The same goes for wine; a customer may want one lighter glass with dinner on Wednesday and a full-strength bottle with friends on Saturday.
Phasing out low-volume labels
Vinarchy is also pruning the thicket of brands inherited through its creation. It has identified Jacob’s Creek, Hardys and Campo Viejo as core global brands and plans to phase out low-volume labels that no longer serve its long-term plans. Battistessa, a marketer by training, sees concentrated investment as crucial. “Wine probably hasn’t historically had the ongoing investment in brand equity in the past,” she said. We can see this across FMCG, where companies concentrate investment behind fewer brands and support them with advertising and strong retail execution. In wine, where provenance can sometimes be expected to perform the entire sales pitch, that approach gives the category a more robust commercial advantage.
Her attitude to retailers follows from that. She wants Vinarchy to discuss total category growth with its major accounts, bringing the category-management habits of Nestlé, Unilever and Kimberly-Clark into wine. The timing is useful, as Australia remains the Australian wine industry’s largest single market, accounting for 40 per cent of Australian wine sales, and domestic performance is proving sturdier than many mature markets overseas. A supplier with Vinarchy’s breadth can chase incremental growth across several price points and occasions, instead of waiting for aggregate consumption to revive.
‘Watch this space’
When Vinarchy officially launched last year, it brought together operations spanning multiple continents, with wines sold across much of the world. Battistessa said that global reach gave the group the ability to create pillar brands and execute ideas across markets, particularly for its Australian portfolio, which ranges from household names such as Jacob’s Creek and Hardys to Grant Burge, St Hugo, Petaluma and Stoneleigh. Another global experiment under way is ‘Welcome to the Creek’, Jacob’s Creek’s new global brand platform aiming to make wine feel more social and approachable. Vinarchy launched it in July and first rolled it out in the UK. Asked whether the platform could reach Australia, Battistessa’s answer was admirably brief: “Watch this space.”
For all the talk of formats and occasions, heritage still has so much commercial influence. Wine Australia’s latest retail data found several premium regions gaining volume this year, including Riverina, King Valley and Yarra Valley. Battistessa understands that provenance remains part of the pleasure for established drinkers, and her task is to widen the vocabulary around it. She talks of “lifestyles”, moderation and accessible formats as the green shoots worth pursuing. The bottle, the region, the winemaker and the dinner table all remain available. Vinarchy simply wants more reasons for shoppers to enter the aisle. “If I have the opportunity to walk out of this role and leave a legacy behind that, turn the category around, put Vinarchy on the growth trajectory, and cement a strong future for the Australian wine industry, I will be one very happy person.” Battistessa has arrived from the far-reaching FMCG world carrying plenty of commercial experience. The wine category is naturally accustomed to talking about what is in the bottle, but she is asking an equally important question: How, when and why will somebody buy it?
Originally published in the October edition of Inside FMCG.


